If you are planning to save money safely in 2026, government-backed small savings schemes can be worth considering. These schemes include the Public Provident Fund (PPF), National Savings Certificate (NSC), Sukanya Samriddhi Account and several Post Office deposit options.
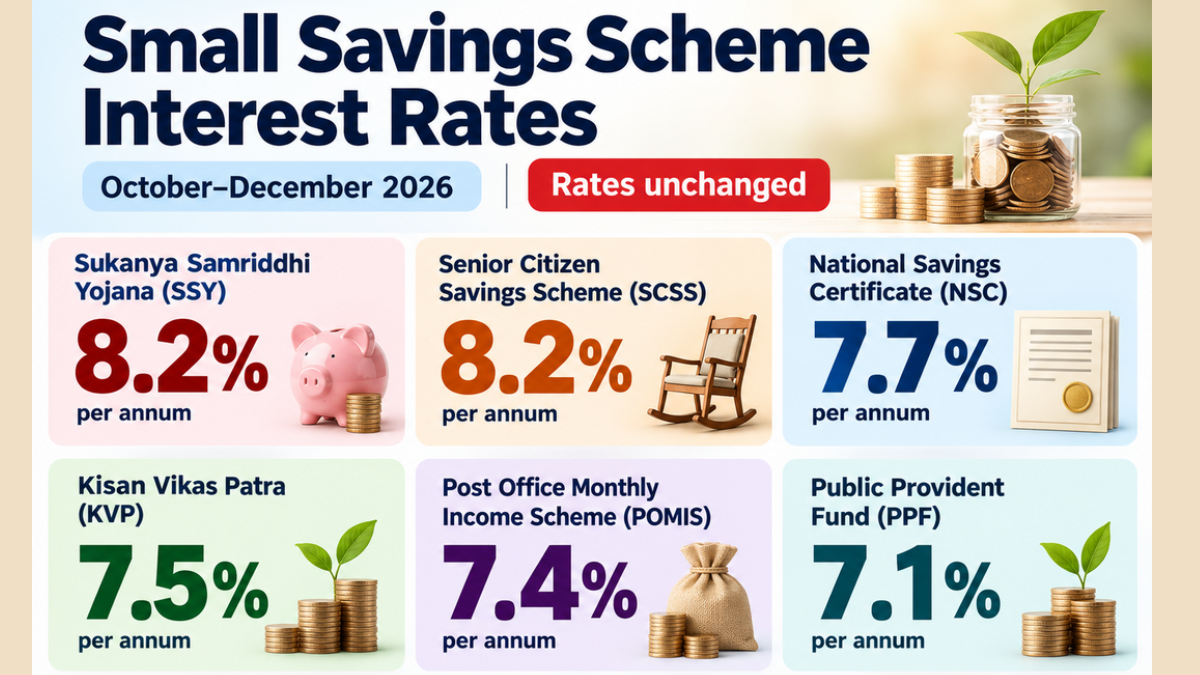
For the October–December 2026 quarter, the government has kept small savings scheme interest rates unchanged from the previous quarter. This means eligible savers can continue to plan their investments using the existing announced rates.
In this guide, Aaj Ka Savings explains the latest rates, the purpose of each scheme and what you should consider before investing.
Small Savings Scheme Interest Rates: October–December 2026
The following interest rates apply for the October 1 to December 31, 2026 quarter.
| Government savings scheme | Annual interest rate |
|---|---|
| Public Provident Fund (PPF) | 7.10% |
| Sukanya Samriddhi Account (SSY) | 8.20% |
| Senior Citizens’ Savings Scheme (SCSS) | 8.20% |
| National Savings Certificate (NSC) | 7.70% |
| Kisan Vikas Patra (KVP) | 7.50% |
| Post Office Monthly Income Scheme (MIS) | 7.40% |
| Post Office 1-Year Time Deposit | 6.90% |
| Post Office 2-Year Time Deposit | 7.00% |
| Post Office 3-Year Time Deposit | 7.10% |
| Post Office 5-Year Time Deposit | 7.50% |
Source: Government small savings interest rate information published by Indian Bank. Rates and calculation methods vary by scheme. Verify the applicable terms before investing.
1. Public Provident Fund (PPF): For Long-Term Savings
The Public Provident Fund offers an announced interest rate of 7.10% per annum for this quarter.
PPF may suit individuals who want to build long-term savings gradually rather than invest money for just a few months.
Key points:
- It has a standard 15-year maturity period, subject to the scheme’s rules.
- Interest is calculated according to the applicable PPF rules.
- Eligible contributions may qualify for tax benefits under applicable tax provisions.
- Partial withdrawals and extensions are subject to specific conditions.
PPF may be worth considering for long-term financial goals, but it is not designed for people who need immediate access to all their savings.
2. Sukanya Samriddhi Account: Savings for a Girl Child
The Sukanya Samriddhi Account offers an announced interest rate of 8.20% per annum for October–December 2026.
This government-backed scheme is intended to help families save for the future education and other eligible needs of a girl child.
Key points:
- The account is subject to eligibility requirements, including rules relating to the girl child’s age.
- Deposits, withdrawals and maturity are governed by scheme-specific conditions.
- Tax treatment depends on the applicable provisions and the investor’s circumstances.
Parents or guardians should check the current eligibility and account-opening rules before making a deposit.
3. Senior Citizens’ Savings Scheme (SCSS)
The Senior Citizens’ Savings Scheme offers an announced interest rate of 8.20% per annum for this quarter.
It is designed for eligible senior citizens who want a government-backed savings option that pays interest periodically.
Before investing, check the eligibility rules, deposit limits, maturity period, premature-closure conditions and tax treatment. The scheme may suit people seeking regular income, but the right choice depends on their overall financial needs.
4. National Savings Certificate (NSC)
The National Savings Certificate offers an announced interest rate of 7.70% per annum for October–December 2026.
NSC is a fixed-term savings instrument available through the Post Office network. It may appeal to people who prefer a defined investment period instead of market-linked returns.
Before investing, review its maturity rules, interest calculation, tax implications and conditions for early access to funds.
5. Post Office Monthly Income Scheme (MIS)
The Post Office Monthly Income Scheme offers an announced interest rate of 7.40% per annum.
As its name suggests, the scheme is designed to provide periodic monthly interest income. It may be relevant for investors who want to supplement their regular income.
However, monthly interest payments are not the same as monthly compounding. Check the current deposit limits, account rules and maturity conditions before opening an account.
6. Post Office Time Deposits: Choose a Suitable Tenure
Post Office Time Deposits offer different interest rates according to the selected term.
For October–December 2026, the announced rates range from 6.90% for a one-year deposit to 7.50% for a five-year deposit.
A longer tenure is not automatically the best option for everyone. Consider when you will need the money, whether premature withdrawal is permitted and what penalties or other conditions may apply.
Should You Invest in Small Savings Schemes in 2026?
There is no single savings product that is best for everyone. Your choice should depend on your goal, time horizon, liquidity needs and tax situation.
Consider these questions before investing:
- What is the goal? Saving for retirement, a child’s future or a short-term expense may require different products.
- When will you need the money? Avoid locking away money you may need for an emergency.
- Do you need regular income? A scheme paying periodic interest may be more relevant than one designed for long-term accumulation.
- What are the tax implications? Check whether interest, contributions or maturity proceeds receive any tax benefit under the rules applicable to you.
- Have you compared alternatives? Compare eligible bank FDs and other suitable savings products, including their terms and risks.
It is also wise to maintain an emergency fund before committing all available savings to long-term products.
Are Small Savings Interest Rates Likely to Change Soon?
Interest rates are reviewed periodically, and future rates should not be assumed to remain the same. The rates listed in this article apply to the October–December 2026 quarter.
If you plan to open a new account or renew an investment, check the latest government notification or official scheme information first.
Frequently Asked Questions
1. Have small savings scheme interest rates changed for October–December 2026?
No. The announced rates have remained unchanged from the previous quarter.
2. Which listed scheme has the highest announced interest rate?
Sukanya Samriddhi Account and Senior Citizens’ Savings Scheme both offer an announced rate of 8.20% per annum for this quarter. They have different eligibility requirements and purposes, so they are not interchangeable.
3. Is PPF suitable for short-term savings?
PPF is primarily a long-term savings option with a standard 15-year maturity period. It may not be appropriate if you need the entire amount soon.
4. Are these returns guaranteed for every future year?
No. The rates stated here apply to the specified quarter and should not be treated as a promise that the same rates will continue indefinitely. Scheme rules and future notifications matter.
5. Where can I verify the latest rates?
Check official government notifications and the relevant bank or India Post scheme information before investing.
Final Thoughts
Small savings schemes can help people build financial discipline and work towards specific goals. The right option depends on how long you can keep your money invested, whether you need regular income and what conditions apply to the scheme.
For October–December 2026, the announced rates remain unchanged. Use this information as a starting point, compare the relevant options and confirm the official terms before making an investment decision.
Disclaimer: This article is for educational purposes only and does not constitute personalised financial or tax advice. Interest rates and scheme conditions may change. Verify the applicable rules with an official source before investing.